

by Henrique Rodrigues
The sudden collapse of Paraguay’s Ueno Bank has triggered an unprecedented shockwave, paralyzing the country’s economy. The digital bank was the processor of roughly two-thirds of all electronic transactions at retail establishments across the country. It saw its operations abruptly shut down, leaving the commercial sector in a state of near-paralysis and plunging the population into a climate of despair and uncertainty over the fate of their finances.
The collapse occurred in the early hours of Tuesday, October 3, when the Central Bank of Paraguay ordered an intervention and the closure of the bank, initiating a liquidation process after identifying a severe solvency crisis. Audited financial statements revealed that the institution’s capitalization ratio had fallen to less than half of the minimum required by national regulations.
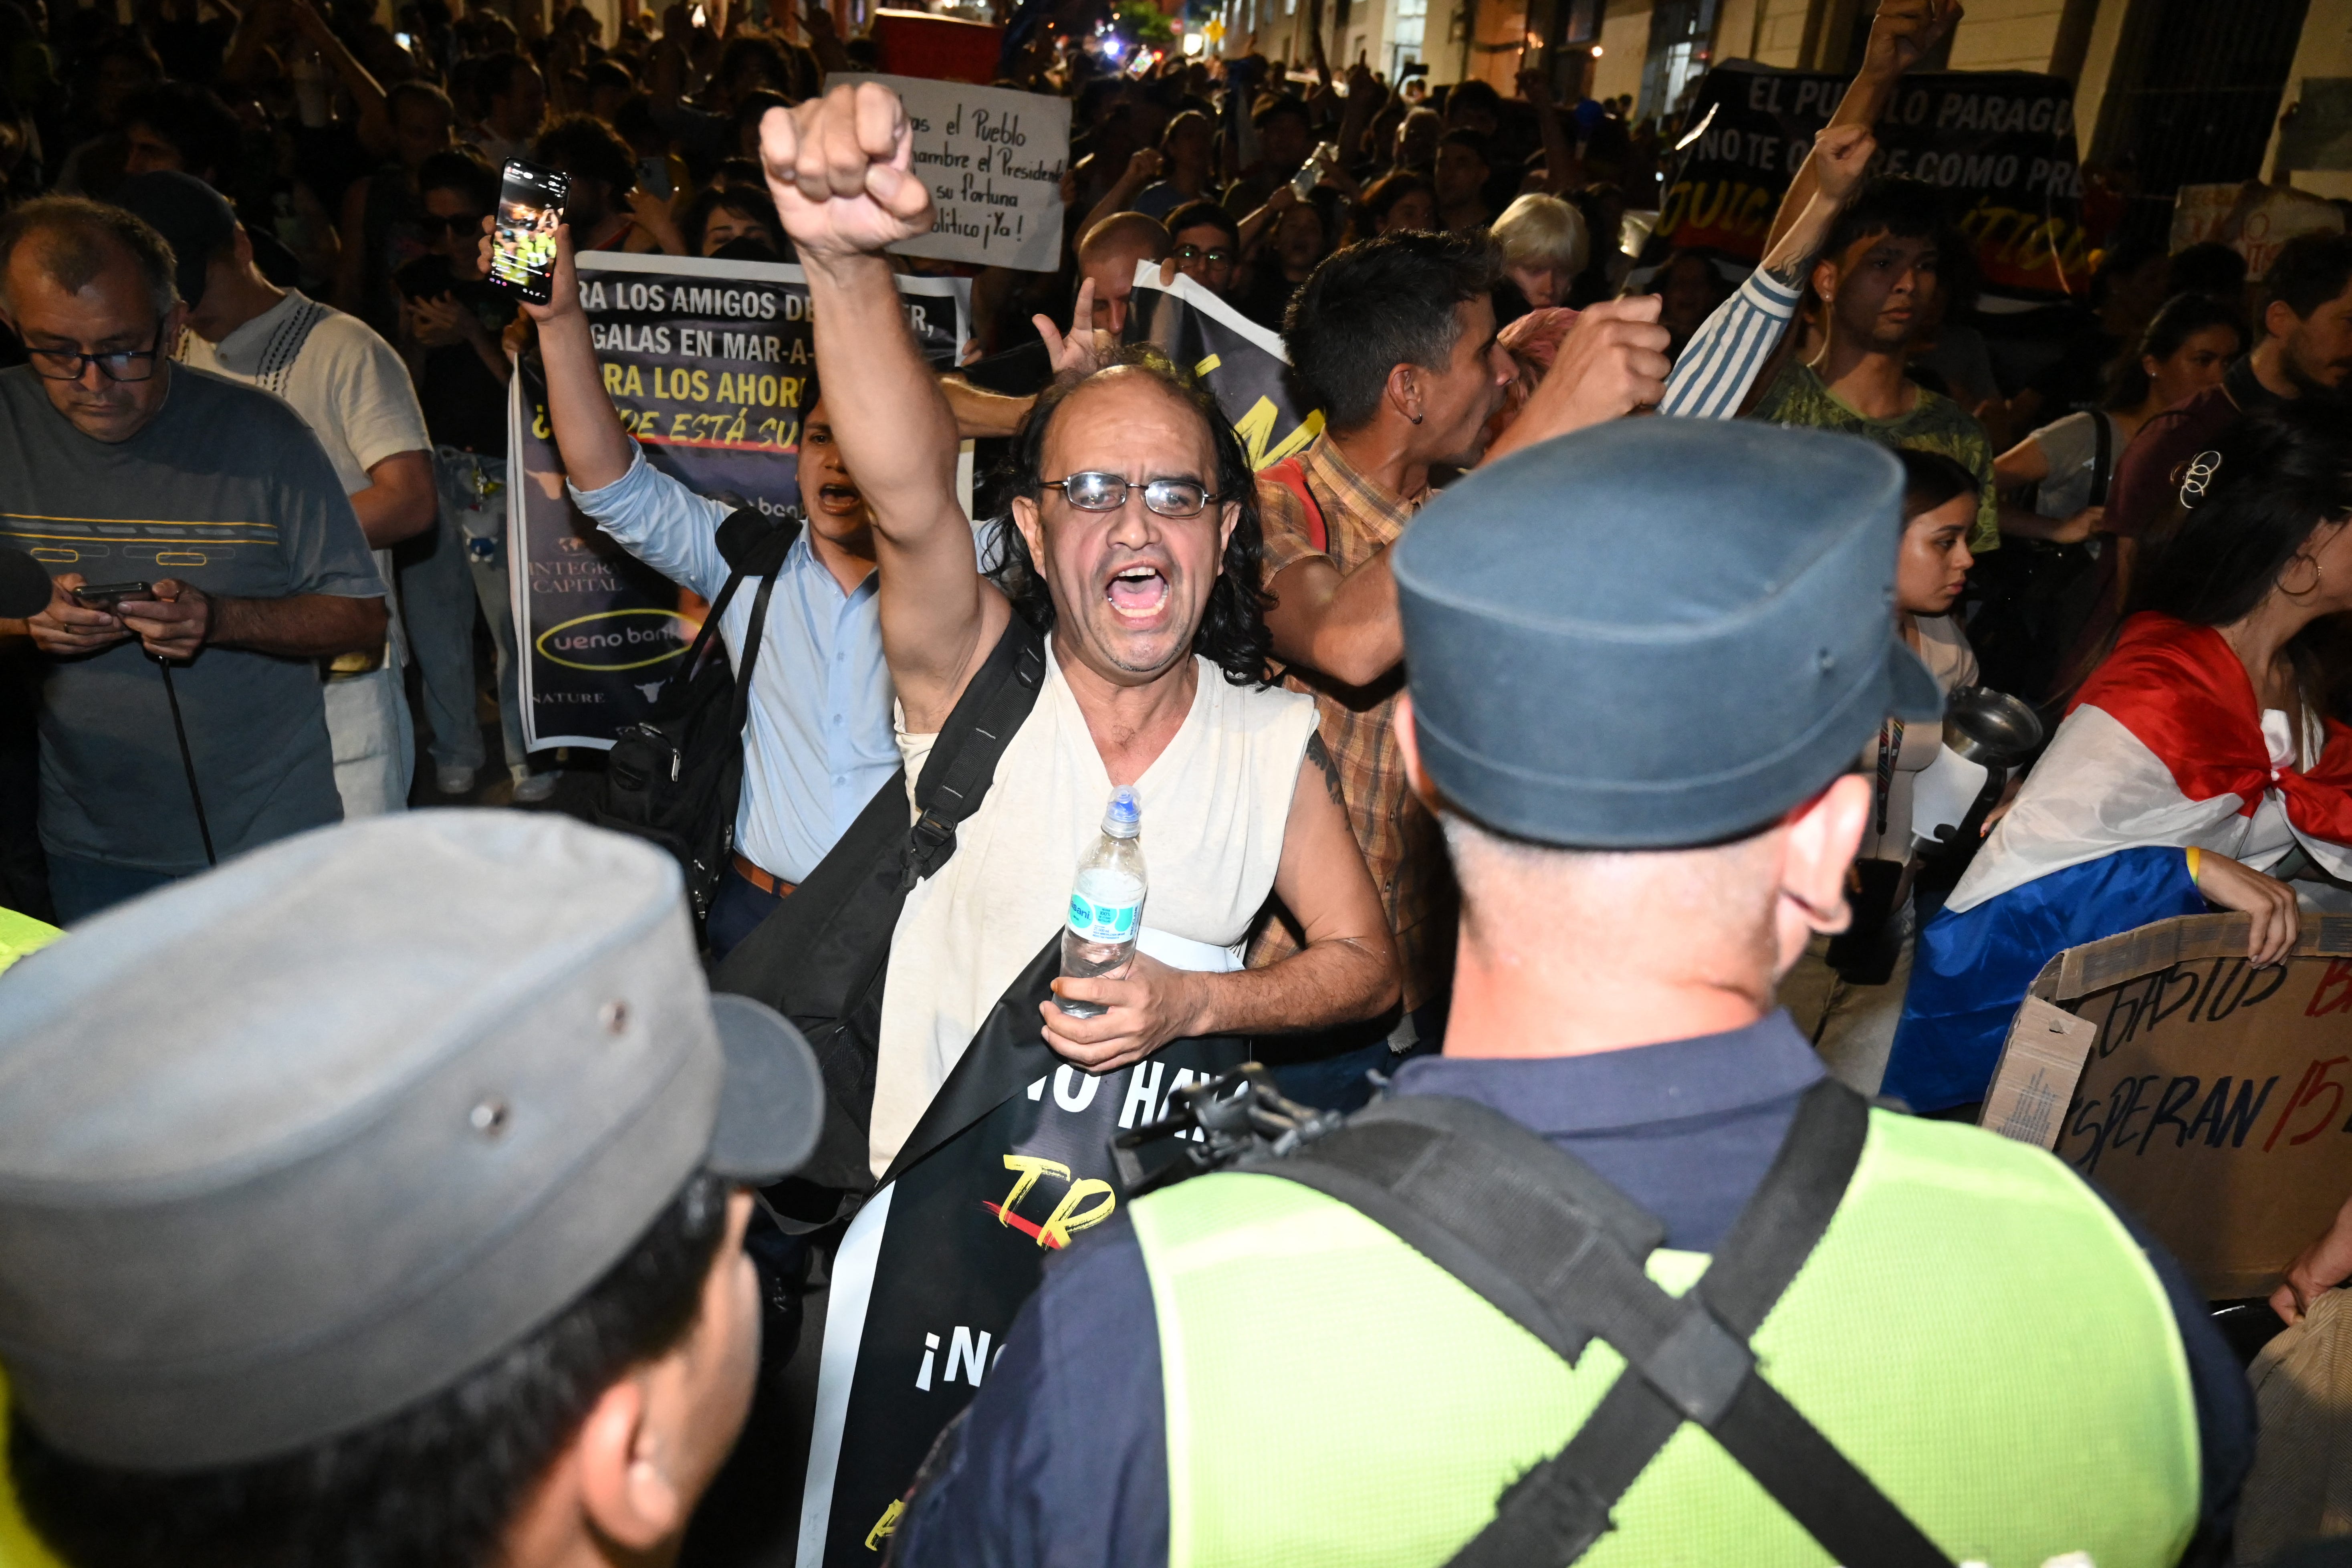
Ueno Bank depositors demonstrate in front of police officers during a protest following the intervention of the bank by Paraguay’s Central Bank in Asuncion on November 3, 2026. (Photo by DANIEL DUARTE / AFP via Getty Images)
The authorities’ response was immediate: the Paraguayan Public Prosecutor’s Office launched a criminal investigation into the bank’s leadership and issued arrest warrants for at least eight executives linked to the controlling entity, the Vázquez Group, including the chairman of the board, Miguel Vázquez.
The crisis has even reached the national political sphere, refocusing attention on Paraguayan President Santiago Peña, who was previously an investor in Ueno Bank’s holding company before selling his stake in March 2025.
Retail Paralysis and Daily Chaos for the Population
With the immediate suspension of all Ueno Bank operations, the impact on the country’s streets has been devastating. The bank had become the backbone of digital payments in Paraguay, amassing over 2.9 million account holders in a nation of approximately 6.1 million people. It was processing more than three million transactions daily.
The service disruption brought about 70% of retail and import-sector sales to a standstill. Unable to process card payments or transfers linked to the digital banks’s app, merchants saw their sale volume collapse, while thousands of citizens found themselves unable to carry out basic daily tasks, like paying for public transport, buying groceries, settling rent, or covering university tuition.
The social crisis is compounded by the impact on vulnerable groups. more than 32,000 retirees used the financial institution to receive their monthly social security benefits from the Social Welfare Institute, IPS, Paraguay’s social security agency.
Panic in the Streets, Tension, and Loss of Faith in the Social Security System
The inability to access one’s own funds, indicated only by error messages on mobile apps, led to growing crowds and protests outside shuttered branches in Asunción, Ciudad del Este, and various towns across the country.
In Ñemby, in the capital’s metropolitan area, the mounting tension culminated in one desperate customer smashing the glass door of a branch while seeking information. Faced with the risk of civil unrest, the National Police placed their forces on high alert and bolstered security around all of the financial institution’s locations nationwide.
The crisis at Ueno Bank has also sounded a red alert over the future of the public social security system. The IPS has approximately US$ 300 million invested or deposited with the liquidated institution, sparking deep concern among the working class that the loss of these assets could compromise the financial sustainability of the pension fund for decades to come.
Promises of Reimbursement and the Erosion of Credibility
To contain widespread panic and prevent a domino effect, the Central Bank of Paraguay was quick to characterize the episode as an isolated event, asserting that the rest of the banking system remains sound. The monetary authority stated that about 97% of account holders have balances covered by the Deposit Guarantee Fund, which ensures the return of up to 228 million guaranis, approximately US$ 37,400 per client.
However, the state guarantee sets a timeframe of up to 15 days for the funds to begin being settled and returned to account holders. For families and small business owners who relied on their daily balances to survive and keep their businesses running, a two-week wait represents an unsustainable gap. The episode has shattered the credibility of digital banks in the country, leaving behind a large number of clients determined to move their funds to traditional institutions as soon as their money is recovered.
This article was originally published by Revista Forum. It was translated by Panamerican Dispatch. You can read the original, in Portuguese, here.